Forex Broker Client Segregation
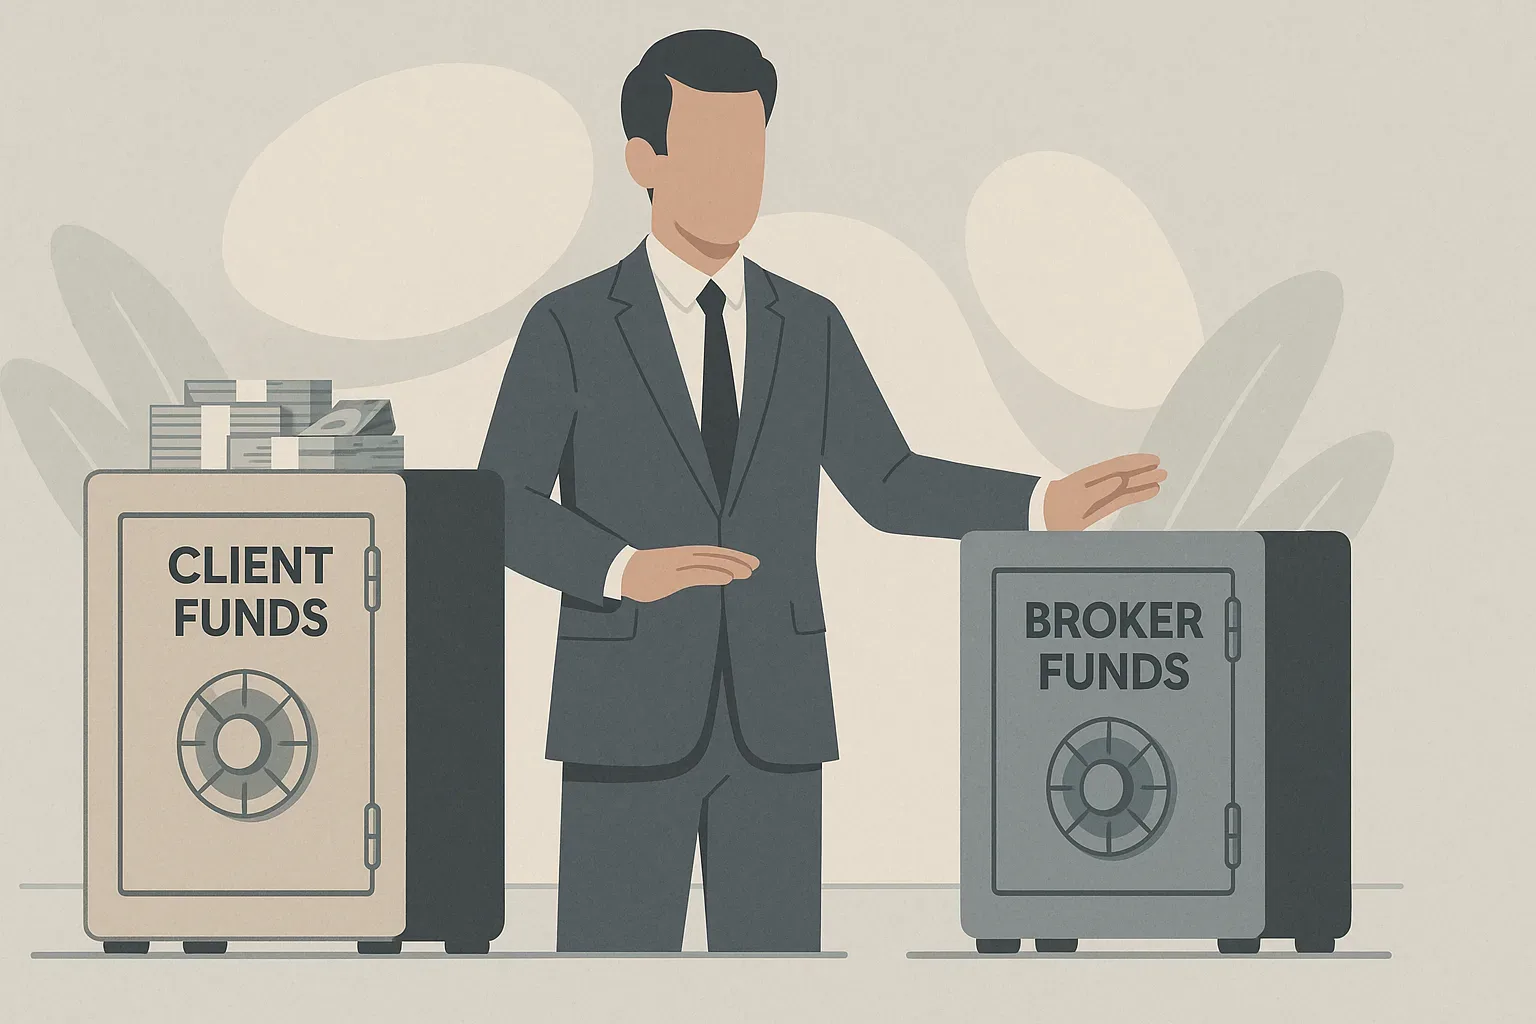
Forex Broker Client Segregation is a critical mechanism designed to protect traders' funds by keeping them separate from a broker's operational capital. This practical guide demystifies its importance, how it works, regulatory standards, and how to identify compliant brokers on Forextoolstrader.com.
This article will demystify forex broker client segregation, detailing its critical role in trader fund protection and how it serves as a key indicator when evaluating reputable trading platforms on Forextoolstrader.com.
Understanding Client Segregation: What It Is and Why It Matters
Client segregation in forex trading is a fundamental principle of financial regulation designed to protect traders' funds. This isn't merely an accounting practice. It's a legal safeguard. Without segregation, a broker's financial difficulties could directly lead to the loss of client funds, as they might be treated as part of the broker's assets subject to creditors' claims. Therefore, segregation ensures that your investment remains your property, held in trust by the broker, rather than becoming part of their balance sheet. This distinction is critical for investor confidence and the overall integrity of the forex market, safeguarding against situations where a broker's commercial failures impact their clients.
The Mechanics of Fund Protection: How Client Segregation Works in Practice
Forex brokers typically implement client fund segregation through a combination of dedicated bank accounts, legal trust arrangements, and robust internal oversight. The most common method involves opening separate bank accounts specifically designated for client funds at reputable, often Tier-1, banking institutions. These are usually referred to as 'client money accounts' or 'trust accounts.' Legally, the funds within these accounts belong to the clients, not the broker. This means that even if the broker were to face bankruptcy, these funds cannot be used by the insolvency administrator to pay off the broker's creditors. This continuous reconciliation process, often subject to external audits, helps prevent discrepancies and ensures that client funds are accurately accounted for and always available for withdrawal. Some brokers may also use omnibus accounts, which group client funds together but still maintain the legal separation from the broker's own capital.
Regulatory Frameworks and Client Fund Segregation Standards
Client fund segregation is not a voluntary best practice but a mandatory requirement enforced by leading financial regulatory bodies across the globe. Each regulator sets specific, stringent standards for how brokers must handle client money. For instance, the Financial Conduct Authority (FCA) in the UK mandates that client funds must be held in segregated client money bank accounts, entirely separate from the firm's own funds, and cannot be used for the firm's own business. The Cyprus Securities and Exchange Commission (CySEC), a prominent European regulator, similarly requires brokers to hold client funds in separate accounts and adhere to strict reporting and reconciliation protocols. In Australia, the Australian Securities and Investments Commission (ASIC) imposes comparable requirements for holding client money in trust. In the United States, the National Futures Association (NFA) and the Commodity Futures Trading Commission (CFTC) have some of the most rigorous rules, requiring futures commission merchants (FCMs) to keep customer funds in segregated accounts and prohibiting their use for proprietary trading. These regulatory bodies routinely audit brokers to ensure compliance with these segregation rules, issuing penalties for violations. You can learn more about these standards by reviewing articles such as https://forextoolstrader.com/article/forex-broker-licensing-requirements.
Segregated Accounts vs. Pooled Accounts: The Critical Difference for Traders
While many jurisdictions require segregated client accounts, some less regulated or offshore brokers might operate with a less stringent approach. A truly segregated account, as mandated by top-tier regulators, means that your funds are legally separated from the broker's operating capital. This ensures that in the event of the broker's insolvency, your money cannot be seized by their creditors. It is protected. However, the critical difference arises when a broker's *own* operating capital is mixed or 'pooled' with client funds without proper legal distinction. This scenario presents immense risks. If a broker's own funds and client funds are not strictly separated, client money can be mistakenly or deliberately used to cover the broker's operational expenses, debts, or trading losses. This blurring of lines removes the vital legal protection that segregation provides, leaving clients vulnerable to significant financial loss if the broker's business fails.
Identifying Compliant Brokers: What to Look for in Trading Platform Reviews
Begin by checking the broker's regulatory status; reputable regulators like the FCA, CySEC, ASIC, or NFA explicitly mandate client fund segregation. Look for the broker's license number and verify it directly on the regulator's website. A legitimate broker will prominently display this information. Next, thoroughly review the broker's legal documentation, including their Terms and Conditions and Client Agreement. These documents should clearly state their policy on client fund segregation, often referencing the specific regulatory requirements they adhere to. Pay attention to clauses about how client money is held, whether in separate bank accounts, and if any investor compensation schemes apply. Reputable brokers will typically provide clear statements on their website regarding fund protection measures. Additionally, independent trading platform reviews and forums can offer insights, though always cross-reference information. A transparent broker will provide clear and satisfactory answers. Lastly, consider the broker's overall reputation and track record, which can often be gleaned from detailed reviews and industry reports.
When Segregation Fails: Risks to Client Funds and Historical Context
The absence of proper segregation means that client funds are commingled with the broker's operational assets. In such a scenario, if the broker faces financial distress, bankruptcy, or even outright fraud, client funds become indistinguishable from the broker's own liabilities. This exposes traders to direct counterparty risk, as their money can be legally claimed by the broker's creditors or frozen indefinitely during insolvency proceedings. A notable example is the collapse of MF Global in 2011, where an estimated $1.6 billion in client funds went missing due to unauthorized transfers to cover the firm's own trading losses. While the specific details involved complex financial maneuvers, the core issue was the failure to adequately segregate client money, leading to a prolonged and painful recovery process for many investors. The ramifications include not only the potential loss of principal but also prolonged legal battles, frozen accounts, and a complete erosion of trust in the financial system. For traders, this translates to an inability to access their funds for an indefinite period, potentially missing out on market opportunities or facing personal financial hardship.
Ensuring Your Capital's Safety: A Checklist for Evaluating Brokers
Here is a checklist to guide your assessment:
- Verify Regulation: Confirm the broker is regulated by a top-tier authority (e.g., FCA, CySEC, ASIC, NFA). Check their license directly on the regulator's official website, not just on the broker's site. This is the foundational layer of protection. * Examine Segregation Policy: Look for explicit statements in the broker's legal documents (Terms and Conditions, Client Agreement) detailing their client fund segregation practices. It should confirm funds are held in separate bank accounts, distinct from company capital. * Identify Banking Partners: Reputable brokers often disclose the names of the Tier-1 banks where client funds are held. This transparency is a good sign, allowing you to gauge the financial strength of the institutions involved. * Check for Compensation Schemes: Determine if the broker is covered by an Investor Compensation Fund (ICF) or similar scheme in their jurisdiction (e.g., FSCS in the UK, ICF in Cyprus). These schemes offer an additional layer of protection, up to a certain limit, in case of broker insolvency. * Review Audit Practices: Inquire about the frequency and independence of external audits of their client money accounts. Regular, independent audits provide assurance that segregation rules are consistently followed. * Assess Broker Reputation: Research the broker's history, read independent reviews on reputable sites, and check for any past regulatory infractions or complaints related to fund handling. Articles that discuss forex broker spreads characteristics or transparency standards, like https://forextoolstrader.com/article/forex-broker-spreads-characteristics and https://forextoolstrader.com/article/forex-broker-transparency-standards, can also indirectly reflect a broker's overall ethical standards. * Test Customer Service: Directly ask the broker's support team about their fund segregation and protection measures. A knowledgeable and transparent response is a positive indicator.
What happens to my capital if a broker with segregated funds faces insolvency?
If a forex broker that genuinely segregates client funds faces insolvency, your capital is generally protected from the broker's creditors, though the process for its return can vary and may not be instantaneous. Because your funds are held in legally separate accounts, meaning they never become the property of the broker, they cannot be used to settle the broker's debts or cover their operational costs. Instead, during an insolvency event, a designated insolvency administrator or liquidator is appointed. Their primary role, concerning segregated client funds, is to identify and ring-fence these assets. The administrator's duty is then to ensure these funds are returned to the rightful clients. This process usually involves verifying individual client balances against the segregated accounts. While the funds are protected, there can be delays in their return due to the administrative procedures of insolvency, which can take several weeks or even months to complete as accounts are reconciled and claims processed. These schemes provide an additional safety net, offering compensation to clients up to a certain monetary limit in the event that a broker becomes insolvent and is unable to return client funds, even if they were segregated. For example, under the UK's Financial Services Compensation Scheme (FSCS), eligible clients can receive compensation up to £85,000.
- forex
- broker
- segregation
- fund protection
- regulation
- safety
- trader education
Related coverage
 ReviewReviews
Forex Broker Licensing Requirements
Forex Broker Licensing Requirements: a practical, no-hype guide for readers from Forextoolstrader Com.
 ReviewReviews
Forex Broker Transparency Standards
Forex Broker Transparency Standards: a practical, no-hype guide for readers from Forextoolstrader Com.
 ReviewReviews
Raxon24 Erfahrungen: Broker-Test von Plattform, Konten und Konditionen
Wir haben Raxon24 (raxon24.com) geprüft: Kontoeröffnung, Handelsplattform, Kontomodelle, Spreads, Gebühren, Ein- und Auszahlungen sowie Support im Überblick.